What Makes a Location ‘High‑Growth’? The Full Checklist for Australian Property Buyers & Investors

In Australian property, location isn’t just important—it’s everything. But not all locations grow at the same pace, and relying on headlines or “hot suburb” lists can be misleading.

True high‑growth locations share a consistent set of underlying characteristics that support long‑term demand, rising prices, and rental strength. This article breaks down the complete checklist professionals use to identify high‑growth areas before the boom becomes obvious.

1. Strong, Sustainable Population Growth

Population growth underpins property demand. More people mean more competition for housing—simple as that.

What matters most is quality and sustainability of growth, not just short‑term spikes.

Look for:

  • Net interstate migration (people choosing to move there)
  • International migration settling long‑term
  • Growing household formation (not just transient renters)
  • Consistent growth over 5–10 years

Areas benefiting from capital city spillover—such as Brisbane, Perth, Adelaide, and key regional hubs—often outperform when migration accelerates.

Red flag: Population growth driven mainly by short‑term workers or students without long‑term settlement.

2. Employment Depth and Economic Diversity

High‑growth locations are supported by jobs—plural. Areas reliant on a single industry (e.g. mining towns) may boom quickly but can crash just as fast.

The strongest locations feature:

  • Multiple employment sectors (health, education, government, tech, logistics)
  • Large “anchor employers” (universities, hospitals, defence bases)
  • Low unemployment relative to the state average
  • Job creation that outpaces population growth

Cities and suburbs with white‑collar job density tend to attract higher‑income households, pushing up both prices and rents long term.

3. Infrastructure Investment (Committed, Not Promised)

Infrastructure drives accessibility, jobs, and desirability—but only once it’s actually funded and underway.

Prioritise locations with:

  • State or federal funding already approved
  • Projects under construction (not just announced)
  • Transport upgrades (rail, motorways, public transport)
  • Health, education, and lifestyle infrastructure

Infrastructure improves commute times and unlocks new buyer pools—often before prices fully reflect the benefit.

Tip: Follow where governments are spending, not just what they’re talking about.

4. Housing Supply Constraints

Capital growth accelerates when demand rises faster than supply.

Strong growth locations often have:

  • Limited land availability
  • Natural boundaries (water, parks, topography)
  • Low rates of new dwelling approvals
  • High owner‑occupier density (less speculative stock)

Inner‑ring suburbs and established middle‑ring areas often outperform fringe locations because supply simply can’t expand quickly.

Red flag: Large greenfield estates with endless land releases.

5. Demographic Profile Trending Upwards

Follow the people—not just the property.

High‑growth areas usually show:

  • Rising median household incomes
  • Educated workforce growth
  • Young professionals upgrading from renting to buying
  • Increasing owner‑occupier ratios

This is known as gentrification in action—and it’s one of the most powerful drivers of sustained capital growth.

6. Lifestyle Appeal and Amenity Access

Lifestyle isn’t a “nice to have”—it’s a demand multiplier.

Buyers pay a premium for places that make life easier and more enjoyable.

Key amenities include:

  • Cafés, restaurants, and retail strips
  • Schools (especially high‑performing public schools)
  • Parks, beaches, and walkability
  • Cultural and recreational facilities

The rise of hybrid work has made amenity‑rich suburbs even more valuable, particularly outside Sydney and Melbourne CBDs.

7. Affordability Relative to Incomes

The best growth often occurs where prices are still affordable relative to local incomes, but improving.

Look for:

  • Purchase prices below the city median
  • Strong serviceability for local households
  • Room for wage growth and buyer upgrading
  • Rental yields that support holding costs

This is the “sweet spot” where demand can expand without hitting affordability ceilings too early.

8. Tight Rental Market

Investor demand follows tenant demand.

Strong rental fundamentals include:

  • Low vacancy rates (typically under 2%)
  • Rising rents over multiple years
  • Diverse tenant pool (families, professionals)
  • Limited new rental supply coming online

A tight rental market often signals future price growth, not the other way around.

9. Market Cycle Positioning

Timing matters.

Some locations boom early, others later. High‑growth investors look for areas that are:

  • Early to mid‑cycle (not peak hype)
  • Beginning to show price momentum
  • Benefiting from a broader city‑wide upswing
  • Still offering value compared to neighbouring suburbs

Often, the best opportunities sit just outside already‑booming suburbs.

10. Local Sentiment & Buyer Activity

Finally, look beyond the data.

Professional buyers watch:

  • Auction clearance trends
  • Days on market falling
  • Buyer competition increasing
  • Owner‑occupier demand rising

When locals start competing aggressively for homes, growth often follows.

Final Thoughts: It’s Never Just One Factor

No single metric creates a high‑growth location. The strongest performers tick multiple boxes simultaneously.

Think of it as a scorecard:

✔ Growing population
✔ Diverse jobs
✔ Infrastructure investment
✔ Supply constraints
✔ Demographic uplift
✔ Lifestyle appeal
✔ Rental pressure
✔ Early‑cycle positioning

The more boxes a location ticks, the stronger its long‑term growth potential.

How to Read Property Market Data Like a Professional

The property market loves a good headline, but if you’re looking to build real wealth, you need to stop reading the news and start reading the numbers.

In the Australian landscape of 2026, we’ve shifted from a “uniform boom” to a “multi-speed market.” While Perth and Brisbane continue to show double-digit momentum, Melbourne and Sydney are offering different value propositions for the patient investor.

To navigate this like a pro, you need to master five key data pillars. Here is how to decode them.

1. Auction Clearance Rates: The “Mood Ring” of the Market

Clearance rates tell you how many properties sold versus how many went to auction. In Australia—particularly in Sydney and Melbourne—this is your most immediate indicator of buyer sentiment.

  • 70%+ (Seller’s Market): Buyers are aggressive. Prices are likely to rise. Expect “FOMO” to drive the market.
  • 60% – 70% (Balanced Market): Supply and demand are in a polite tug-of-war. This is a great time to negotiate.
  • Below 60% (Buyer’s Market): Properties are “passing in.” Sellers are getting nervous. This is where the best deals are found.

Pro Tip: Don’t just look at the percentage. Check the Volume. A 70% clearance rate on 1,000 auctions is far more significant than 70% on 10 auctions.

2. Days on Market (DOM) & Vendor Discounting

If the clearance rate is the “mood,” DOM is the “momentum.” It measures how long it takes for a property to go from “For Sale” to “Under Contract.”

  • Low DOM (Under 20 days): The market is hot. If you don’t have your finance ready, you’ve already lost.
  • Vendor Discounting: This is the difference between the original asking price and the final sale price. In 2026, we are seeing tight discounting (0% to -2%) in Perth and Adelaide, signaling that buyers have zero leverage. If discounting starts to widen (to -5% or more), the power is shifting back to you.

3. The “Vacancy Rate” vs. Rental Yields

For investors, the vacancy rate is the single most important number for cash flow safety.

  • The 3% Rule: A “balanced” rental market has a vacancy rate of roughly 3%.
  • The 2026 Reality: Most Australian capitals are currently sitting near record lows of 1.1% to 1.5%. This means high rental competition and upward pressure on rents.
  • Gross Rental Yield: Calculate this as:Gross Rental Yield = (Annual Rental Income/Property Value) × 100 With interest rates hovering between 2.8% and 4% this year, pros are looking for yields that help offset holding costs—often targeting units in Brisbane or regional hubs where yields remain stronger than houses.

4. Median Price vs. “Stratified” Growth

The “Median House Price” is the most quoted stat, but it can be misleading. It’s simply the middle point of all sales.

  • The Trap: If a suburb has a sudden influx of luxury sales, the median jumps, even if the “average” house didn’t increase in value.
  • The Pro Move: Look at quartile data. In 2026, the “lower quartile” (affordable entry-level homes) is outperforming the “upper quartile” (luxury) because of high borrowing costs and government first-home buyer schemes.

5. Supply Pipeline (Building Approvals)

The “Holy Grail” of property growth is scarcity.

Check the Australian Bureau of Statistics (ABS) for “Building Approvals” in your target LGA (Local Government Area). If approvals are falling while population growth is rising, you’ve found a recipe for capital growth. In 2026, the national housing shortage remains a primary driver for prices, as construction struggles to hit government targets.

Summary: Your 2026 Cheat Sheet

Indicator Bullish Signal (Prices Up) Bearish Signal (Prices Down)
Auction Clearance Above 70% Below 55%
Vacancy Rate Below 1.5% Above 4%
Days on Market Decreasing (Trend) Increasing (Trend)
Stock on Market Low/Falling supply High/Rising supply

Final Thought

Professional investors don’t buy “The Australian Property Market”—they buy a specific street in a specific suburb based on data. Use tools like CoreLogic (Cotality), SQM Research, and the ABS to find the “speed” of your specific micro-market.

The Pros and Cons of Dual Income Properties

Let’s be real: in 2026, the “standard” rental property is starting to feel a bit outdated. With interest rates doing their thing and the cost of living hitting everyone’s pockets, investors are looking for a way to make their money work double-time: the dual income property.

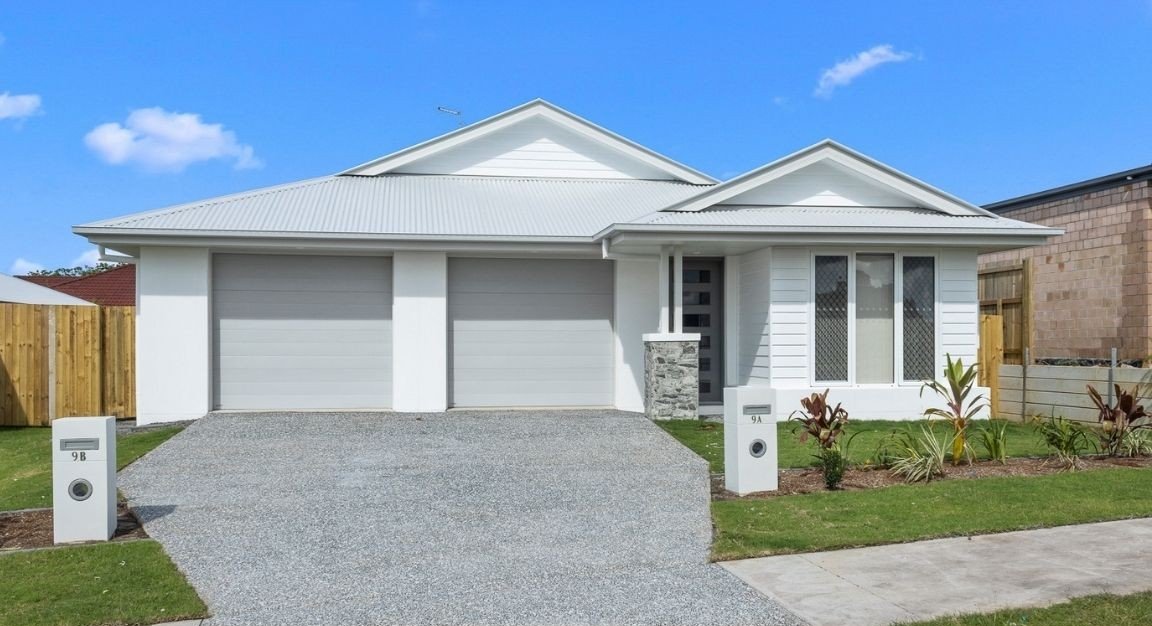
Think of it as the ultimate “two-for-one” deal in real estate. Whether it’s a duplex, a house with a trendy granny flat out back, or a dual-key apartment, the vibe is simple: one mortgage, two rent checks. It sounds like a total dream for your cash flow, right? But before you start picking out two sets of kitchen appliances, there’s a bit more to it than just collecting extra rent. You’re also looking at double the maintenance and—let’s face it—double the tenant drama.

So, is doubling up actually the genius move it looks like on paper? Let’s break down the pros and cons of the dual-income life.

The Pros: Why Investors Love Them

1. Superior Rental Yields

The most obvious benefit is the “two-for-one” deal. Typically, the combined rent of two smaller units is significantly higher than the rent of one large family home on the same land. In high-demand urban areas, this can mean the difference between a property that’s “negatively geared” (costing you money) and one that is cash-flow positive from day one.

2. Reduced Vacancy Risk

If a single-tenant property goes vacant, your income drops to zero. With a dual-income setup, if one tenant moves out, you still have the other 50% of your income to help cover the mortgage while you hunt for a new renter.

3. Tax Efficiency & Depreciation

Since you have two kitchens, two sets of appliances, and potentially two hot water systems, your depreciation schedule is much more aggressive. In 2026, where every tax deduction counts, being able to write off the “wear and tear” of two dwellings against your income is a massive win.

4. Maximized Land Utility

Land is the appreciating asset; the building is the depreciating one. Dual occupancy allows you to squeeze the maximum utility out of your land, essentially doubling your “inventory” without the cost of buying a second lot.

The Cons: The Hidden Challenges

1. Higher Initial Construction & Setup Costs

Building two dwellings—even if they share a wall—is more expensive than building one. You’ll face double the “wet area” costs (plumbing for two kitchens and multiple bathrooms) and higher council contribution fees for the second “address.”

2. Privacy & Tenant Disputes

Unless the dwellings are completely detached with separate street frontages, tenants will be sharing a fence, a driveway, or even a backyard.

  • The “Noise” Factor: Common walls in older duplexes can lead to noise complaints.
  • The “Parking” War: If there isn’t clearly designated parking for both units, it’s the #1 source of tenant friction.

3. Management Overhead

You aren’t just managing a property; you’re managing a mini-community. If the tenant in Unit A hates the music coming from Unit B, you are the referee. While a property manager can handle this, expect to pay slightly more for the complexity of managing two separate leases on one title.

4. Resale Limitations

While investors love dual-income properties, the owner-occupier market (the largest pool of buyers) often avoids them. Most families want a big backyard to themselves, not a neighbor living 10 feet away in a “granny flat.” This can sometimes limit your capital growth compared to a traditional standalone house.

2026 Strategy Table: Is it Right for You?

Feature Dual Income Property Traditional Single-Family Home
Cash Flow High / Positive Low / Often Negative
Maintenance Higher (two of everything) Standard
Exit Strategy Best for Investors Best for Families
Financing Can be stricter (LVR limits) Generally easier

The Bottom Line

Dual-income properties are for the yield-seeker. If your goal is to replace your salary with rental income as quickly as possible, the dual-check system is hard to beat. However, if you prefer a “set and forget” investment with minimal drama, a traditional house in a blue-chip suburb might still be your best bet.

Build‑to‑Rent vs Build‑to‑Sell: Which Is Better for Your Investment Goals?

In the 2026 Australian property landscape, the choice between Build-to-Rent (BTR) and Build-to-Sell (BTS) is no longer just a matter of preference—it’s a strategic decision shaped by high construction costs, shifting tax laws, and a chronic housing undersupply.

While the “Great Australian Dream” of homeownership still fuels the BTS market, the BTR sector has evolved from a niche institutional play into a cornerstone of the modern rental market. Here is a breakdown of how these two models compare for your investment goals.


1. Build-to-Sell (BTS): The Traditional Powerhouse

The BTS model involves developing a property (usually apartments or townhouses) and selling the individual units upon completion.

The Investor Profile

Best for those seeking short-to-medium-term capital injection and investors who want to recycle their equity quickly.

The Pros

  • Lump Sum Returns: You realize your profit immediately after the project is finalized and the “sunset clause” or settlement occurs.
  • Lower Management Burden: Once the keys are handed over, your responsibility ends. There is no need for long-term property management or maintenance logistics.
  • GST Recovery: In Australia, BTS developers can typically claim GST credits on construction and land costs, which can effectively lower project costs by 10% compared to BTR.

The Cons

  • Market Timing Risk: You are highly exposed to the property cycle. If the market dips during your 18-to-24-month build, your profit margins can evaporate by settlement.
  • Transactional Costs: Each sale incurs high agent fees, marketing costs, and legal fees.

2. Build-to-Rent (BTR): The Modern Income Engine

In a BTR project, the developer (or an investor group) retains ownership of the entire building and manages it as a single-income-producing asset.

The Investor Profile

Best for long-term wealth builders and institutional-grade investors looking for stable, “bond-like” cash flow and high tenant retention.

The Pros

  • Stabilised Yields: Because BTR buildings are professionally managed with high-end amenities (gyms, co-working spaces), they often command a 5–10% rental premium over traditional private rentals.
  • Tax Incentives (New for 2026): Recent federal reforms allow eligible BTR projects to access an accelerated capital works deduction of 4% (up from 2.5%) and a concessional 15% Managed Investment Trust (MIT) withholding tax rate on income and capital gains.
  • Occupancy Stability: BTR projects in Australia currently maintain occupancy rates above 95% due to the security of tenure they offer renters.

The Cons

  • Capital Lock-up: Your money is tied up for the long haul. BTR is an endurance game, often requiring a 10-to-15-year commitment to maximize tax benefits.
  • GST “Leaking”: Unlike BTS, BTR developers currently cannot claim GST credits on construction costs, making the initial build roughly 10% more expensive upfront.

Side-by-Side Comparison

FeatureBuild-to-Sell (BTS)Build-to-Rent (BTR)
Primary GoalCapital Gains / Profit MarginYield / Long-term Cash Flow
LiquidityHigh (Once completed)Low (Long-term hold)
Tax TreatmentGST Credits available15% MIT Concession (if eligible)
Operational RiskMarket cycle at time of saleManagement and maintenance costs
Tenant StabilityN/A (Sold to owners/investors)Very High (Professional management)

The 2026 Verdict: Which is “Better”?

Choose Build-to-Sell if:

You need to grow your capital base rapidly. With Sydney and Melbourne dwelling values still showing resilience, a well-timed BTS project can provide the “seed money” for larger future investments. It remains the more straightforward path for smaller, private developers.

Choose Build-to-Rent if:

You are prioritizing income security in an inflationary environment. As of 2026, the Australian rental market remains in a state of chronic undersupply. BTR allows you to capture this demand while benefiting from the government’s 15-year compliance incentives. It is the “defensive” play for a volatile market.

Why New Builds Are Gaining Investor Momentum in 2026

The Australian property landscape of 2026 looks remarkably different from the “growth at all costs” era of the early 2020s. With national median home prices in capital cities having surpassed the $1 million mark and the Reserve Bank of Australia maintaining a cash rate of 3.85% as of February, investors have shifted their strategy.

While established homes were once the default choice, a unique convergence of tax benefits, energy regulations, and supply shortages has pushed “New Builds” to the forefront of the savvy investor’s radar.


1. The “Depreciation Gap” is Widening

In 2026, the tax advantage of a new build isn’t just a “nice to have”—it’s a critical component of portfolio cash flow. Following legislative changes, investors in established properties (purchased after 2017) generally cannot claim depreciation on “plant and equipment” (removable assets like ovens, carpets, and air cons) that they didn’t personally buy new.

New builds, however, allow for full depreciation claims on both:

  • Division 43 (Capital Works): The structure of the building itself (bricks, mortar, and wiring).
  • Division 40 (Plant and Equipment): Brand-new appliances and fixtures.

For a typical $650,000 investment, a new build can generate $10,000–$18,000 in tax deductions in its first year, compared to roughly $4,000–$8,000 for an established equivalent. In a high-interest environment, these paper losses are a lifeline for negative gearing strategies.


2. The 7-Star Standard & Lower Holding Costs

The National Construction Code (NCC) 2025, which officially commences on 1 May 2026, has set a high bar for energy efficiency. All new homes must now achieve a minimum 7-star NatHERS rating.

Why this matters for investors:

  • Tenant Retention: With energy prices remaining a concern for households, a 7-star home is significantly cheaper to heat and cool, making it a “premium” choice for long-term tenants.
  • Maintenance “Holiday”: New builds come with builder warranties (often 6 years or more for structural issues). In 2026, when tradie labor costs remain high, the absence of “surprise” repairs on a new property protects your net yield.

3. Government Incentives: Shared Equity & Build-to-Rent

The 2025–26 Federal Budget introduced several “carrots” for those adding to the housing supply rather than just trading existing stock:

  • The Help to Buy Scheme: While primarily for home buyers, the government’s 40% equity contribution for new builds (vs. 30% for established) has stimulated the construction sector, ensuring a steady flow of high-quality stock for investors to buy into via off-the-plan opportunities.
  • Build-to-Rent (BTR) Concessions: New tax incentives have accelerated the BTR sector. For larger-scale investors, the Capital Works deduction rate has increased from 2.5% to 4%, allowing construction costs to be written off over 25 years instead of 40.

4. Smart Entry Prices in “Fringe” Hubs

As established prices in Sydney and Melbourne push affordability to its limits, investors are looking at greenfield estates in high-growth corridors such as South East Queensland, Perth, and Western Sydney.

FactorNew Build (2026)Established (2026)
Stamp DutyOften on land only (if H&L)Full property value
Initial YieldApprox. 4–5% (gross)Approx. 3–4% (gross)
Annual MaintenanceMinimal / Under Warranty$3,000–$8,000 estimated
Tax Deductions$10k+ (Year 1)$5k average (Year 1)

The Verdict: Cash Flow vs. Capital Growth

The “Old Guard” of property investing still swears by established land value, and they aren’t entirely wrong—established homes in blue-chip suburbs often see higher long-term capital appreciation.

However, in 2026, the narrative has changed. Investors are prioritizing yield and tax efficiency to combat higher mortgage repayments. By opting for a new build, you are essentially “buying” a tax refund and a low-maintenance lifestyle, making it the preferred vehicle for those looking to survive—and thrive—in the current economic climate.

House & Land vs Townhouses vs Units – What Works Best in Today’s Market?

In 2026, the Australian property market is no longer a simple race where “land always wins.” For decades, the mantra was that a freestanding house on a big block was the only path to wealth. But as we navigate a landscape of high construction costs, a chronic housing shortage, and a “two-speed” market, the rules have changed.

Whether you’re a first-home buyer trying to break the rent cycle or an investor looking for yield, here is how House & Land, Townhouses, and Units stack up in today’s market.


1. House & Land: The “Blue Chip” Capital Growth Play

Traditionally, the “Great Australian Dream” is built on the fact that land appreciates while buildings depreciate. In 2026, this remains true for long-term wealth, but the entry price has reached an all-time high.

  • Market Status: Standalone houses in major capitals like Sydney and Melbourne now command a massive price premium—often 70% higher than the median unit price.
  • The 2026 Edge: Scarcity is your best friend. With councils pushing for higher density, a freestanding block in an established suburb is a “limited edition” asset.
  • Best For: Long-term investors (10+ years) and families who prioritize privacy and the freedom to renovate.

Pro Tip: In 2026, “House & Land” packages in outer-growth corridors are seeing slower growth than houses in “middle-ring” suburbs. Focus on locations with established infrastructure rather than just new grass.


2. Townhouses: The “Goldilocks” Solution

Townhouses have emerged as the MVP of the 2026 market. They offer a middle ground: more space than an apartment, but more affordable than a house.

  • Market Status: Townhouses are currently outperforming houses in “pull-through” demand. When buyers are priced out of houses, they don’t go to units—they go to townhouses.
  • The 2026 Edge: They hit the “sweet spot” for the two largest buyer demographics: Downsizers (who want low-maintenance luxury) and Young Professionals (who want a home office and a small courtyard).
  • Best For: Those who want a “lock-and-leave” lifestyle without sacrificing the feeling of a “real” home.

3. Units/Apartments: The Yield & Affordability King

2026 has been a “comeback year” for the humble unit. With national vacancy rates hovering near record lows (below 1% in cities like Perth and Brisbane), units are no longer the “compromise” choice.

  • Market Status: In many LGAs, unit price growth is actually outpacing houses. For example, in Brisbane and Perth, over 75% of unit markets matched or beat house growth in the last year.
  • The 2026 Edge:Rental Yield. Units typically offer gross yields of 4.5% to 6%, significantly higher than the 3% to 3.5% seen in houses. This makes them much easier to “hold” as interest rates fluctuate.
  • Best For: Cash-flow-heavy investors and first-home buyers using government schemes (like the First Home Guarantee) to enter the market with a smaller deposit.

Comparing the Three: At a Glance

FeatureHouse & LandTownhouseUnit / Apartment
Price PointHighestMid-rangeMost Affordable
Capital GrowthHigh (Land-driven)Strong (Demand-driven)Moderate (Location-driven)
Rental YieldLower (~3.5%)Solid (~4.2%)Highest (~5%+)
MaintenanceHigh (Your responsibility)Low (Body Corporate)Very Low (Strata)
ControlFull AutonomyLimited by BylawsStrict Strata Rules

The Verdict: What works best in 2026?

The “best” choice depends on your Exit Strategy:

  1. If you want to build massive equity over 20 years: Stick with House & Land. The land component is a hedge against inflation and a finite resource in our growing cities.
  2. If you are a First Home Buyer in a capital city: Look at Boutique Townhouses. They offer the best balance of lifestyle and future resale value without the $1.5M+ price tag.
  3. If you need cash flow to service your mortgage:Units in “walkable” suburbs (near cafes, transport, and hospitals) are the winners. Avoid high-rise “cookie-cutter” towers; focus on boutique blocks with low strata fees.

The Golden Rule for 2026: Location and scarcity now matter more than the dwelling type. A well-located unit in a prime suburb will likely outperform a house in a remote suburb with no public transport.

5 Suburb Growth Indicators Every Investor Must Know

In the fast-moving 2026 property market, the difference between a “good” investment and a “wealth-building” one often comes down to timing. While the national market is projected to grow by roughly 7.7% this year, savvy investors aren’t looking at national averages—they’re looking for the micro-signals that a specific suburb is about to outperform.

Here is your 2026 checklist for identifying high-growth suburbs in the current Australian landscape.


1. Days on Market (DOM): The Speed of Sale

In 2026, the national average for property sales has tightened to roughly 29 days. However, in “hot” zones like Perth and parts of Brisbane, we are seeing medians as low as 9 to 15 days.

  • The Indicator: Watch for a consistent downward trend in DOM over 3-6 months.
  • The 2026 Rule: If a suburb’s DOM is under 20 days, it’s a high-pressure zone. When properties sell before the first open home, a price jump is usually only weeks away.

2. Vacancy Rates: The Scarcity Factor

The rental market is the ultimate leading indicator for capital growth. With capital city vacancies hovering around a record low of 1.1% to 1.3% in early 2026, the competition for housing is fierce.

  • The Indicator: Look for suburbs with vacancy rates under 1%.
  • The Logic: Ultra-low vacancy leads to urgent rent hikes. As yields rise, investors flock to the area, which then pushes up property prices.

3. The “20-Minute Neighborhood” & EV Infrastructure

The definition of a “prime location” has evolved. In 2026, buyers are prioritizing self-contained lifestyle hubs over traditional CBD proximity.

  • The Indicator: Suburbs with high “walkability” scores and “green” infrastructure.
  • The 2026 Shift: Look for the arrival of public EV charging hubs and energy-efficient building DAs. According to recent 2026 trends, “EV Ready” homes are now outperforming “NBN Ready” homes in buyer desirability.

4. The “Ripple Effect” (Neighboring Suburb Lag)

Property growth moves like a wave. When a “Blue Chip” suburb (like New Farm in Brisbane or Surry Hills in Sydney) becomes unaffordable, the next suburb over is the immediate beneficiary.

  • How to spot it: Identify a suburb that has grown 10%+ in the last year. Look at its direct neighbors.
  • The Opportunity: If the neighboring suburb has the same school catchment or train line access but is 15-20% cheaper, the “ripple” is about to hit.

5. Gentrification: The “Turn-Key” Premium

Because construction costs remain high in 2026, the old advice of “buy a renovator’s delight” has changed. Today’s investors are looking for suburbs where household incomes are rising, but the stock is “turn-key” (ready to move in).

  • The Indicator: An influx of boutique cafes, “wellness” hubs (Pilates/Yoga studios), and a decreasing median age in Census data.
  • The Signal: When young professionals start outbidding developers for renovated cottages, the suburb’s price ceiling is being fundamentally reset.

2026 Investment Benchmarks

Metric2026 National Average“Growth Hotspot” Signal
Days on Market29 Days< 15 Days
Vacancy Rate1.2%< 0.8%
Vendor Discount2.9%< 1.5%
Rental Yield3.5% – 4.2%> 5.0%

The Bottom Line

Investing in 2026 requires a “micro” focus. While cities like Perth and Brisbane are leading the charge with double-digit growth forecasts, hidden gems exist in Melbourne and Sydney for those who can spot these five indicators before the rest of the market catches on.

Where the Australian Market Is Heading: Key Trends to Watch in 2026

Australia enters 2026 with a blend of optimism, caution, and transformation. After several years of economic recalibration—shaped by global inflation cycles, shifting trade dynamics, and rapid technological adoption—the Australian market is poised for meaningful change. Whether you’re an investor, business owner, or simply curious about the country’s economic direction, understanding the forces shaping the year ahead is essential.

Below are the key trends that will define Australia’s market landscape in 2026—and why they matter.

1. A Softening Inflation Environment and Stabilising Interest Rates

After a turbulent period of rate hikes, 2026 is shaping up to be the year Australia finally finds its monetary footing. Inflation is expected to continue easing toward the Reserve Bank of Australia’s target range, giving policymakers room to hold—or even gradually reduce—interest rates.

What this means for the market:

  • Borrowing conditions may improve for households and businesses
  • Consumer confidence could rebound, supporting retail and services
  • Property markets may see renewed activity, especially in major cities

Investors will be watching the RBA closely, as even small policy shifts could influence equity valuations and currency movements.

2. Renewables and Clean Tech Take Centre Stage

Australia’s energy transition is accelerating. With government incentives, private capital, and global climate commitments aligning, 2026 will be a pivotal year for renewable energy and clean‑tech innovation.

Expect growth in:

  • Solar and wind infrastructure
  • Green hydrogen projects
  • Battery storage and grid‑modernisation technologies
  • Carbon‑capture and emissions‑reduction solutions

Companies in these sectors are likely to attract strong investment interest as Australia positions itself as a regional clean‑energy powerhouse.

3. AI and Automation Reshape Business Operations

AI adoption is no longer experimental—it’s becoming foundational. From mining to healthcare to finance, Australian industries are integrating automation and machine learning to boost productivity and reduce costs.

Key shifts to watch:

  • AI‑driven customer service and analytics
  • Autonomous machinery in mining and agriculture
  • Digital twins in construction and infrastructure
  • Workforce upskilling and new tech‑centric job roles

Businesses that embrace AI early will gain a competitive edge, while laggards may struggle to keep pace.

4. Housing Affordability Pressures Persist

Despite potential rate stabilisation, Australia’s housing market remains structurally tight. Population growth, limited supply, and construction bottlenecks continue to push prices upward.

Likely outcomes in 2026:

  • Continued demand for build‑to‑rent developments
  • Increased government focus on zoning and supply reform
  • Rising interest in regional and outer‑metro areas
  • Strong rental market conditions

Property investors will need to navigate a landscape where demand remains high but affordability challenges shape consumer behaviour.

5. The Rise of the “Asia‑Pacific Advantage”

Australia’s geographic and economic ties to the Asia‑Pacific region are becoming even more valuable. As global supply chains diversify and regional trade strengthens, Australian exporters are well‑positioned to benefit.

Sectors to watch:

  • Agriculture and food exports
  • Critical minerals (especially lithium and rare earths)
  • Education and tourism
  • Technology partnerships with Southeast Asia

Expect increased collaboration, investment flows, and cross‑border innovation.

6. Consumer Behaviour Shifts Toward Value and Experience

Australian consumers are becoming more selective. Even as economic conditions improve, shoppers are prioritising value, sustainability, and meaningful experiences.

Emerging trends:

  • Growth in second‑hand and circular‑economy marketplaces
  • Premium spending on travel, wellness, and lifestyle experiences
  • Continued shift toward online and hybrid retail models
  • Brand loyalty driven by authenticity and social impact

Businesses that understand these evolving preferences will thrive.

7. Cybersecurity Becomes a Boardroom Priority

With cyber incidents rising across the globe, Australian organisations are investing heavily in digital security. In 2026, cybersecurity is no longer an IT issue—it’s a strategic imperative.

Expect:

  • Increased spending on threat detection and prevention
  • Stricter compliance requirements
  • Growth in cybersecurity talent demand
  • More partnerships between the government and private sector

Companies that fail to prioritise cyber resilience risk financial and reputational damage.

Looking Ahead

The Australian market in 2026 is defined by transformation—economic, technological, and social. While challenges remain, the opportunities are significant for those who stay informed and adaptable. Whether you’re investing, building a business, or planning your next strategic move, understanding these trends will help you navigate the year with clarity and confidence.

The Hidden Costs of Property Investing and How to Prepare for Them in 2026

Property investment remains a cornerstone of wealth-building in Australia—strong population growth, tight rental markets, and expected price rises of 7–10% nationally in 2026 make it appealing. But the dream of passive income often collides with reality: hidden costs that erode yields and surprise even experienced investors.

In 2026, with insurance premiums surging due to extreme weather events, holding costs averaging at least 2.6% per year (per RBA estimates), and state-specific taxes like land tax biting harder, many “positive cash flow” deals turn neutral or negative if not planned for.

Here are the most common hidden costs Australian property investors face, backed by recent data, plus practical steps to protect your returns.

1. Maintenance, Repairs, and Capital Expenditure (Capex)

Why it’s hidden: Properties wear out—tenants accelerate damage, and big-ticket items hit unexpectedly.

Real numbers in 2026:

  • Budget 1% of property value annually for maintenance (~$7,500–$10,000 for a $750,000–$1m property).
  • Major repairs (roof, HVAC, plumbing, hot water system) can cost $5,000–$20,000+.
  • Deferred maintenance or tenant issues add up fast.

How to prepare:

  • Set aside 1–2% of value per year in a dedicated sinking fund.
  • Get comprehensive building & pest inspections pre-purchase.
  • Consider landlord insurance with good coverage for tenant damage.
  • Opt for newer or low-maintenance properties where possible.

2. Insurance Premiums – The Fastest-Rising Cost

Why it’s hidden: Premiums feel fixed until renewal—then climate-driven hikes shock.

Current trends:

  • Home and contents/landlord insurance rose ~14% nationally in 2025 (up to $700 extra annually for some), with 2026 likely similar due to $3.5b+ in extreme weather claims.
  • Flood/bushfire-prone areas see even steeper increases; some owners question future insurability.

How to prepare:

  • Shop quotes annually—compare via comparison sites.
  • Bundle landlord insurance with building cover.
  • Factor in 10–20% annual increases in your cash-flow forecasts.
  • Improve property resilience (e.g., better drainage) to potentially lower premiums.

3. Vacancy Periods and Turnover

Why it’s hidden: No rent comes in, but fixed costs (mortgage, rates, insurance) continue.

Real impact:

  • Average vacancy is 2–4 weeks per changeover in most markets.
  • One month vacant can erase months of slim positive cash flow.
  • Letting fees, advertising, cleaning, and minor touch-ups add $500–$2,000 per turnover.

How to prepare:

  • Build in 5–10% vacancy allowance in projections (higher in regional or competitive areas).
  • Screen tenants thoroughly and price rent market-competitively.
  • Maintain the property well—happy tenants stay longer.
  • Keep 3–6 months of expenses in reserves.

4. Land Tax – State-Specific Sting

Why it’s hidden: Only kicks in above thresholds, but catches many investors off-guard.

2025–2026 rates (examples):

  • NSW: Threshold $1,075,000; then 1.6% + premium rates above $6.57m.
  • VIC: Lower thresholds (~$50,000–$300,000 range); up to 2.65% on high values.
  • QLD: Threshold ~$600,000–$2m depending on type; up to 2.25%.
  • Other states vary—foreign owners often pay surcharges.

How to prepare:

  • Research your state’s thresholds and rates before buying.
  • Structure ownership (e.g., trusts) carefully—consult a tax advisor.
  • Factor land tax into annual holding costs from day one.

5. Strata/Body Corporate Fees (for Units, Townhouses, Apartments)

Why it’s hidden: These can jump with special levies for major works.

Real numbers:

  • Range from $2,000–$10,000+ annually (or $30–$600/week in extreme cases).
  • Covers common areas (lifts, pools, gardens, exteriors), insurance, and sinking funds.
  • Special assessments for big repairs can add thousands unexpectedly.

How to prepare:

  • Review the strata report and recent meeting minutes pre-purchase.
  • Budget conservatively and ask about upcoming works.
  • Prefer complexes with healthy sinking funds to avoid surprises.

6. Property Management and Administrative Costs

Why it’s hidden: Self-managing saves fees but costs time/stress; pros take 5–12% of rent.

Other fees:

  • Tenant placement/leasing (~1–2 weeks rent).
  • Accounting, tax prep, and ATO compliance.
  • Eviction/legal costs if issues arise.

How to prepare:

  • Decide early: self-manage (if local/experienced) or hire a manager (8% average).
  • Track all expenses meticulously—many are tax-deductible.
  • Use apps/software for rent collection and record-keeping.

7. Upfront and Closing Costs That Add Up

Why it’s hidden: Beyond the deposit, these hit before you collect rent.

Examples:

  • Stamp duty: $20,000–$50,000+ on a $600k–$1m property (varies by state).
  • Conveyancing/legal: $1,000–$2,500.
  • Building/pest inspections: $400–$800.
  • Lenders mortgage insurance (if <20% deposit): $10,000–$30,000+.
  • Loan establishment/fees.

How to prepare:

  • Get full loan estimates early.
  • Negotiate seller contributions where possible.
  • Budget 5–10% extra on top of the purchase price.

8. Tax on Rental Income and Depreciation Opportunities

Why it’s hidden: Rental income is taxable, but many miss deductions like depreciation.

How to prepare:

  • Get a quantity surveyor report for depreciation schedules—can save thousands annually.
  • Claim interest, repairs, management fees, etc.
  • Understand negative gearing benefits, but run realistic after-tax numbers.

Final Thoughts: Make Hidden Costs Predictable in 2026

Australian property can deliver strong long-term returns, but success in 2026 demands treating it as a business: conservative budgeting, buffers, and professional advice.

Quick investor checklist:

  • Use the 50% rule (or more conservative): Expect 50%+ of gross rent to cover expenses (excluding mortgage).
  • Build 6–12 months of holding costs in emergency reserves.
  • Run detailed cash-flow models, including worst-case scenarios (vacancy, repairs, rate rises).
  • Consult experts: buyers’ agents, accountants, tax advisors, and property managers.
  • Review your portfolio annually—costs evolve with markets and climate risks.

The market rewards prepared investors. With yields tight and costs rising, those who account for the “hidden” ones often come out ahead.

Smart investing in 2026—stay prepared!

Understanding Cash Flow vs Capital Growth: Which Should You Prioritise

When building wealth through investing, one of the most common questions is whether to focus on cash flow or capital growth. Both strategies can help you reach financial independence—but each works differently, comes with its own risks, and fits different goals.

This guide breaks down how each strategy works and helps you decide which one to prioritise based on your financial situation and long‑term plans.


What Is Cash Flow?

Cash flow refers to the regular income generated from an investment after expenses.
In property investing, this usually means the net rental income you earn each month.
In business or stocks, it could be dividends or distributions.

Pros of Cash Flow

  • Provides steady, predictable income
  • Helps cover living expenses or reinvest further
  • Offers more stability during market downturns
  • Reduces financial stress—your investment pays for itself

Cons of Cash Flow

  • Cash‑flow properties or investments may grow slower in value
  • Higher rental yields often exist in lower‑growth areas
  • Income can fluctuate with vacancy or market conditions

What Is Capital Growth?

Capital growth is the increase in the value of an asset over time.
For example, buying a property for $500,000 and selling at $700,000 means $200,000 in capital growth.

Pros of Capital Growth

  • Builds wealth faster over the long term
  • Allows leverage—borrow against higher equity
  • Often found in high‑demand, well‑located areas
  • Can significantly accelerate financial freedom

Cons of Capital Growth

  • Income may be low or negative (negative cash flow)
  • Requires long‑term holding to realise gains
  • Higher financial pressure if the asset doesn’t pay for itself

Cash Flow vs Capital Growth: Key Differences

FactorCash FlowCapital Growth
Primary BenefitMonthly incomeLong-term wealth
Risk LevelLowerHigher
Time HorizonShort to medium termLong term
Ideal forIncome seekersWealth builders
Market SensitivityLess affected by price declinesDepends heavily on market cycles

Which Should You Prioritise?

The right strategy depends on your goals, risk tolerance, and financial stage.

1. If you need income now → Prioritise Cash Flow

Great for:

  • Young families needing extra income
  • Early retirement or FIRE strategy
  • Investors who value stability

Cash flow helps you stay afloat while still growing your portfolio slowly.


2. If you want to maximise long‑term wealth → Prioritise Capital Growth

Best suited for:

  • Younger investors with long time horizons
  • People with stable incomes
  • Those planning to build equity and scale

Capital growth creates significant wealth, even if it doesn’t produce high short‑term income.


3. If you want balanced wealth and stability → Use a Hybrid Strategy

Many successful investors combine both:

  • Start with capital growth assets to build equity
  • Add cash‑flow properties later to support the portfolio
  • Achieve both wealth and income over time

This “blend” creates a portfolio that grows fast and helps pay for itself.


How to Decide in 3 Simple Questions

Ask yourself:

  1. Do I need income or wealth first?
  2. How long can I hold an investment?
  3. What is my comfort level with financial risk?

Your answers will guide you naturally toward cash flow, growth, or a combination of the two.


Final Thoughts

There is no “one‑size‑fits‑all” strategy. The best investors understand that cash flow keeps you in the game, while capital growth creates long-term wealth. Prioritise the one that aligns with your financial goals—and remember, you can always shift strategies as your circumstances evolve.